As a general principle, VAT liability – or so called "tax point" – is triggered by the occurrence of a taxable transaction. Specifically, liability arises on the date the sales proceeds are received or when the taxpayer obtains documentary evidence entitling them to such proceeds. However, if an invoice is issued prior to payment or the entitlement to payment, the date of invoice issuance takes precedence.
Building upon these general rules, the Ministry of Finance (MOF) and the State Taxation Administration (STA) issuedAnnouncement [2026] No. 13 on January 30, 2026. Part IV of this Announcement provides critical clarifications regarding the timing of VAT liability under several specialized transaction circumstances.
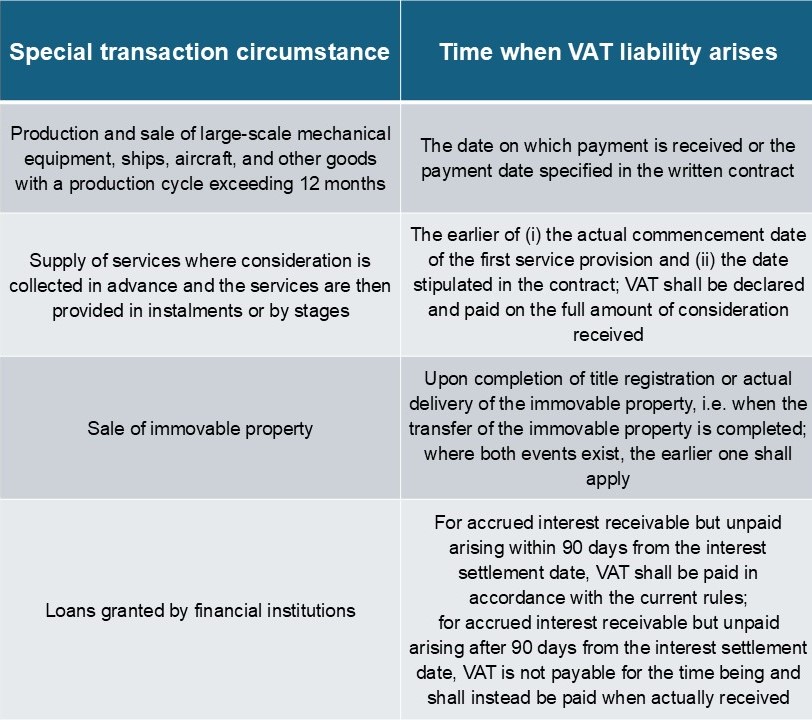
Accordingly, the time when VAT liability arises does not depend entirely on the timing of revenue recognition for accounting purposes. Instead, it is determined more by tax-law criteria such as payment arrangements, contractual terms, the commencement of performance, the fact of delivery, and changes in legal title.
Of particular note, where consideration is collected in advance and services are then provided in instalments, the tax rules expressly require VAT liability to be recognized at the earlier of “the date on which the provision of services actually commences for the first time” and “the date stipulated in the contract,” and VAT must be declared on the full amount received.
At PHC Advisory, we can offer you full support on matters regarding doing business in China, or any other issues your business may face. If you would like to know more about policies relevant to your business in Italy or Asia, please contact us at info@phcadvisory.com.
PHC Advisory is a company of DP Group: an international professional services conglomerate of companies with approximately 100 experienced professionals worldwide. We offer comprehensive services in tax, accounting, and financial consulting, including financial supervision, financial audit, internal audit, internal control over financial reporting, and support for audited financial statements and annual audits, ensuring clients' financial transparency and compliance.
Would you like to learn more about the business environment in China? Click the link and download our Practical Guides on Amazon!
The content of this article is provided for informational purposes only, financial advice must be tailored to the specific circumstances on a case-by-case basis, and the contents of this article do not legally bind PHC Advisory with the reader in any way.